AFSL and ACL licensees often measure control activity because activity is easy to count. Reviews completed. Attestations received. Training delivered. Files checked. Reports submitted. Remedial actions closed.
These measures show that work occurred. They do not establish that the control achieved its purpose.
That distinction is critical. A control can operate exactly as designed and still fail to manage the relevant risk. It can also appear effective because testing is too narrow, too predictable or too dependent on the people who perform it.
The result is false assurance: confidence based on completion rather than evidence of effectiveness.
Testing must begin with the control objective
Effective testing starts by asking what the control is meant to prevent, detect or correct.
A review control may be designed to identify unsuitable advice. A complaints control may be intended to detect systemic customer harm. A training control may seek to improve conduct or decision quality. A remediation control may be intended to prevent recurrence.
Testing should therefore examine whether the intended outcome was achieved.
For an adviser review, it is not enough to confirm that the review template was completed. Testing should consider whether the sample was appropriate, whether the reviewer identified material issues, whether judgements were consistent and whether findings led to effective action.
For training, attendance records show participation. They do not show whether employees understood the material, changed their behaviour or applied the requirement correctly.
For remediation, task closure shows that an action was completed. It does not show whether the root cause was addressed or whether the failure has stopped recurring.
Control testing becomes meaningful when it moves from “Was the step completed?” to “Did the control change the risk?”
Independent validation strengthens assurance
Control owners are usually best placed to explain how a control operates. They are not always best placed to conclude that it is effective.
Independent validation provides challenge. It may be performed by compliance, risk, internal audit, an external reviewer or another function sufficiently separate from the control’s operation.
Independence does not require every control to be externally audited. It requires the level of challenge to match the importance of the control and the consequences of failure.
A low-risk administrative control may justify supervisory review. A control supporting a material licence obligation, vulnerable customer outcome or breach-reporting process may require more rigorous validation.
The key question is whether the reviewer can test the control objectively, challenge assumptions and reach a conclusion that is not shaped by responsibility for the original activity.
Recurring failures are evidence about the control environment
Repeated complaints, incidents, monitoring findings or breaches should not be treated as isolated events by default.
They may indicate that a control is poorly designed, inconsistently performed or directed at the wrong cause. They may also show that remediation is closing tasks without changing the underlying process.
Recurring failures are particularly important where each event falls below a materiality threshold. Individually, they may appear minor. Collectively, they can reveal a systemic weakness.
A mature assurance process connects these signals. It asks whether the same product, representative, workflow, customer group or decision point appears across different records.
Without connected evidence, a licensee can repeatedly investigate symptoms while preserving the condition that produces them.
Risk weighting determines where assurance effort belongs
Not every control requires the same testing frequency, sample size or independence.
Risk-weighted assurance directs effort according to the significance of the obligation, the likelihood and consequence of failure, the control’s complexity, previous findings and the reliability of available evidence.
A high-risk control with repeated exceptions should receive deeper and more frequent testing. A stable control with strong evidence and no adverse indicators may justify lighter-touch review.
Risk weighting also prevents assurance programs from becoming exercises in equal coverage. Testing every control on the same cycle can create the appearance of discipline while diverting attention from the areas where failure would matter most.
Governance requires a conclusion
Testing results do not become governance intelligence until someone reaches and records a conclusion.
That conclusion should state whether the control is effective, partially effective or ineffective, together with the evidence, limitations and actions required.
It should also identify residual risk. A control may be operating but still leave exposure above the organisation’s tolerance. Conversely, an isolated failure may not establish that the entire control is ineffective.
Responsible Managers and boards need these distinctions. They need to understand not only how many controls were tested, but what those tests mean for the organisation’s ability to meet its obligations.
What this means in practice
Licensees should ask:
- Is testing aligned to the control’s intended outcome?
- Is the level of independent challenge proportionate to the risk?
- Are recurring failures analysed across systems and reporting periods?
- Does assurance distinguish completion from effectiveness?
- Do governance reports state a clear conclusion and residual risk?
How [complyᵉ] supports this
[complyᵉ] helps licensees connect controls to testing activity, findings, evidence, remediation and governance conclusions.
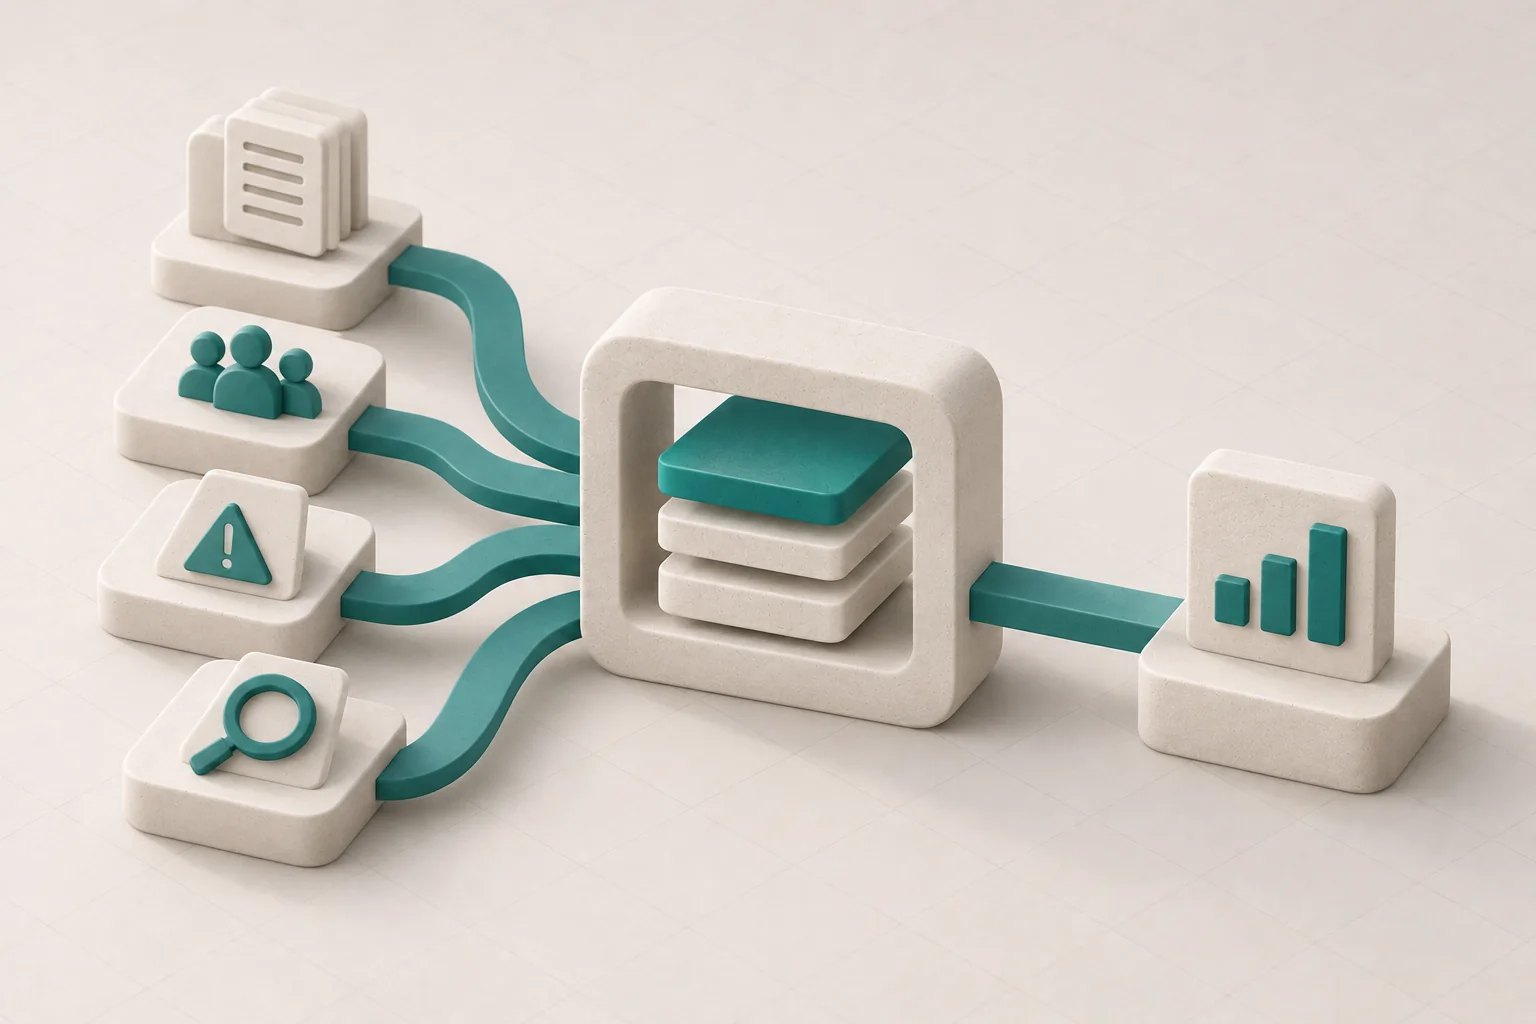
It supports risk-weighted testing programs, preserves review and decision trails, and helps identify recurring weaknesses across complaints, incidents, monitoring and other compliance processes. This gives Responsible Managers and boards a clearer view of which controls are operating, which are failing and where further judgement is required.
Technology does not determine whether a control is legally sufficient or replace independent professional judgement. It helps ensure that conclusions are supported by connected evidence.
A completed control creates activity. A tested and evidenced control creates assurance.